Experts have designed these Class 9 SST Notes and NCERT Class 9 SST Chapter 9 The Price Puzzle What Drives the Market Notes for effective learning.
Class 9 The Price Puzzle What Drives the Market Notes
Class 9 SST Chapter 9 The Price Puzzle What Drives the Market Notes
Class 9 SST Chapter 9 Notes – The Price Puzzle What Drives the Market Notes Class 9
- A market is a place where buyers and sellers interact to exchange goods and services.
- Changes in prices are not random. They are influenced by factors such as seasons, festivals, trends, consumer preferences, rumours, and availability of goods.
- Prices are mainly determined by the interaction of demand and supply.
Demand
- Demand is the quantity of a product that consumers are willing and able to buy at a particular price.
- It depends on consumers’ needs, preferences, season, trend, and their income.
- Mere desire to buy is not demand; consumers must also have the ability (purchasing power) to buy.
- Purchasing power refers to the quantity of goods and services that one unit of currency can buy at a given time.
- According to the Law of Demand, when the price of a good rises, its quantity demanded falls, and when the price falls, quantity demanded increases, assuming other factors remain constant.
- There is an inverse relationship between price and quantity demanded.
- Individual demand refers to the quantity demanded by a single consumer at different prices while assuming other factors are constant.
- A Demand Schedule shows the quantity demanded at different prices in tabular form.
- A Demand Curve is the graphical representation of the demand schedule and slopes downward from left to right, showing the inverse relationship between price and quantity demanded.
For example: Individual Demand Schedule
| Price of Strawberries (₹ per kg) | Quantity Demanded by Pinki (kg) |
| ₹ 60 | 1 |
| ₹ 40 | 2 |
| ₹ 20 | 3 |
1. Individual Demand Curve (Based on Individual Demand Schedule)
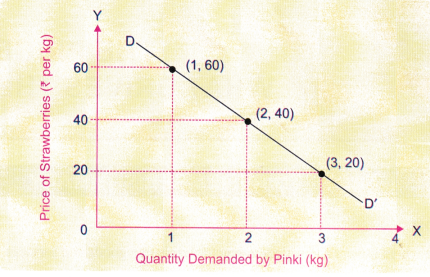
Observation: As the price of Strawberries falls, the quantity demanded by Pinki increases. This illustrates the Law of Demand.
Market demand is the total demand of all potential consumers in the market at different prices and is obtained by adding individual demands.
For example: Market Demand Schedule
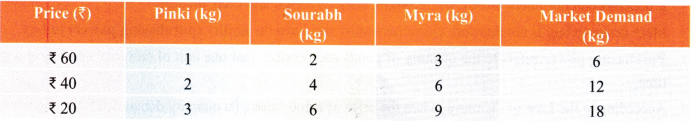
2. Market Demand Curve (Based on Market Demand Schedule)
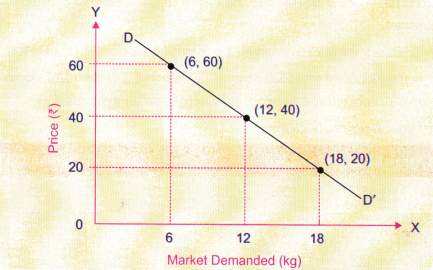
Observation: Market demand is obtained by adding the individual demands of all consumers at different prices.
The market demand curve is flatter than an individual demand curve because it combines the demand responses of many consumers.
Other Determinants of Demand
Price of Related Goods
Demand is influenced by the prices of related goods. They are of two types:
1. Substitute goods and 2. Complementary goods
Substitute goods: These goods can replace each other (e.g., tea and coffee, mangoes and bananas). When the price of one good rises, consumers switch to the other, thus increasing its demand.
Complementary goods: These goods are used together (e.g., smartphones and earphones, cars and petrol). A change in the price or demand of one good affects the demand for the other. A rise in the price of one good, or fall in its demand, reduces the demand for the other.
Income of the Consumer
A rise in household income makes consumers more confident about spending and allows them to buy more or better-quality products, which increases demand even if prices remain unchanged.
Taste and Preference of the Buyer
- Individual tastes, preferences, habits, and choices influence the demand for goods and services.
- Demand depends on the size and composition of the population.
- A larger population increases overall consumer demand.
- Different age groups create demand for different products and services.
Diminishing Marginal Utility
- The additional satisfaction (utility) from consuming successive units of the same product gradually decreases.
- As utility decreases, consumers become less willing to buy additional units, reducing demand.
For example a person gets bored by eating strawberries daily for few days.
Seasonality
- Demand varies with weather, festivals, school sessions, and cultural practices.
- Seasonal demand changes even when prices remain unchanged.
For example, demand of sweets increases during festival seasons.
Future Price Expectations
- Expectations of future price changes affect present demand.
- Consumers postpone purchases if they expect prices to fall but buy earlier if they expect prices to rise.
For instance, consumers wait until the festival season to purchase goods because of good discounts.
Supply
- Supply refers to the amount of a product that sellers are willing and able to sell at a specific price.
- According to the Law of Supply, rise in price of a product leads to more manufactures to come in the market to make profit. Similarly, as price of a product decreases, less manufacturers compete and supply becomes less.
- Higher prices increase profitability, encourage existing producers to expand production and attract new producers.
- Individual supply refers to the quantity supplied by a single seller at various prices.
Economics
Example: At the beginning of the apple season, the supply of apples is low, making apples costly. During the middle of season, supply increases and prices fall. This shows that prices depend on the interaction of demand and supply.
- Supply < Demand, price rise
- Supply > Demand, price fall.
A Supply Schedule presents quantities supplied at different prices.
A Supply Curve graphically represents supply and slopes upward from left to right because price and quantity supplied move in the same direction.
For example: Individual Supply Schedule
| Price of Apples (₹ per kg) | Quantity Supplied by Seller A (kg) |
| ₹ 25 | 1 |
| ₹ 50 | 2 |
| ₹ 75 | 3 |
3. Individual Supply Curve (Based on Individual Supply Schedule)

Observation: As the price increases, the quantity supplied also increases. This illustrates the Law of Supply.
Market supply is the total quantity supplied by all individual sellers in the market.
For example: Market Supply Schedule

4. Market Supply Curve (Based on Market Supply Schedule)

Observation: Market supply is the total quantity supplied by all sellers at each price.
- Market supply is obtained by adding the individual supplies of all producers.
- Prices rise when supply is less than demand and fall when supply exceeds demand.
Other Determinants of Supply Price of Related Goods
Producers allocate resources towards goods thdt provide higher profits.
A rise in the price of one product may reduce the supply of another.
Example: If com prices are low but barley prices are high, a farmer will grow more barley in the next season. Therefore, the supply of com decreases while the supply of barley will increase in the next season.
Number of Sellers in the Market
- Increased competition among producers raises supply, which may exceed demand and leads to a fall in price.
- When there are fewer sellers in the market, supply decreases below demand, leading to higher prices.
Technology
- Improved technology reduces production costs and increases productivity and supply.
- Better technology, improved farming methods, weather sensors, and cold storage facilities increase supply.
Future Expectations
- Producers increase production if they expect higher future demand.
- Producers may reduce production or withhold supply if they expect lower demand or higher future prices.
Market Equilibrium
Market equilibrium is the point where quantity demanded equals quantity supplied and prices are determined by the interaction of demand and supply.
At equilibrium:
- There is neither excess demand (shortage) nor excess supply (surplus).
- The market clears efficiently.
- Prices remain stable unless external conditions change.
If demand exceeds supply, there is excess demand, causing prices to rise.
If supply exceeds demand, there is excess supply, causing prices to fall.
Graphically, equilibrium occurs where the demand curve intersects the supply curve.
For example: Market Equilibrium Schedule

Equilibrium Price = ₹ 50
Equilibrium Quantity = 15 kg

Observation: At ₹ 25, there is excess demand.
- At ₹ 50, demand equals supply, resulting in market equilibrium.
- At ₹ 75, there is excess supply.
Does Market Equilibrium Exist in the Real World?
- In reality, markets are dynamic and constantly adjust to changing conditions.
- Equilibrium continuously shifts because demand and supply change over time.
- Factors affecting equilibrium include: technological changes, changes in wages and interest rates, wars and political events, pandemics, weather and natural disasters.
Example: During the COVID-19 pandemic, the demand for face masks increased sharply, causing prices to rise until supply adjusted.
Tariffs By Hotels: An Example Of Dynamic Markets
- Real-world markets are dynamic because prices continuously respond to changes in demand and supply.
- Hotel room tariffs (price) are an example of dynamic pricing.
- Hotel prices depend on: seasonal demand, festivals and holidays, booking trends, nearby competitors’ prices, Weather forecasts, time remaining before arrival and special events and conferences.
- Businesses frequently adjust prices to maximise revenue.
- Revenue is total money a business earns from selling goods or services before any expenses are ^ deducted.
- Sustainable use of resources is important because present consumption affects future supply and market equilibrium.
Role of Government In The Economy
- At present, India ranks as the fourth-largest economy in the world.
- India follows a market-based regulated economy where prices are mainly determined by demand and supply.
- In markets, goods and services are provided according to consumers’ willingness and ability to pay, but they may not always allocate resources fairly, especially for essential goods.
For example, if medicines become very expensive, many people may then find them difficult to afford. Therefore, fair distribution is important. - The government intervenes to ensure fairness, equity, and the welfare of vulnerable sections of society.
Regulation of Unfair Practices
- Government regulations help protect consumers, workers, and producers by regulating unfair practices and preventing exploitation and injustices.
- Price Ceiling sets the maximum legal price for essential goods and services.
- Price Floor sets the minimum legal price or wage to protect producers and workers.
- The government regulates monopolies to prevent excessive pricing, restricted supply, poor quality, and exploitation by monitoring the prices and quantity supplied in check.
- During emergencies, the government may control prices and prevent hoarding and black marketing to ensure fair distribution of essential commodities.
Many Government regulators are working for benefits of Consumer and few main ones are as follows:
- TRAI (Telecom Regulatory Authority of India) protect rights telecom services including mobile phone, internet etc.
- RBI (Reserve Bank of India) protects rights of Consumers in Banking services.
- CCPA (The Central Consumer Protection Authority) restricts unfair trade practices & protects consumer rights.
- SEBI (The Securities and Exchange Board of India) regulates the Stock markets in India and protect investors.
During covid-19, the demand for sanitisers increased, causing shortages and higher prices. The government controlled prices of sanitisers by bringing them under the Essential Commodities Act, 1955, making them essential commodities and increasing their supply to ensure their availability.
Provision of Public Goods
- Goods and services which are provided by the government for the public are known as public goods.
- Examples: roads, bridges, public parks, street lighting, national defence, sanitation and drainage systems, etc.
- Public goods are generally not produced by private firms because they do not make direct profit.
- Government provision ensures: social welfare, equal access, economic development and availability of essential public services.
Limitations of Government Intervention
Excessive government involvement in the market can have negative impact such as:
(a) Price Distortions and Reduced Producer Incentives
- Government’s artificially low prices reduce producers’ profits.
- Lower profitability discourages production and may create shortages.
(b) Compliance Burdens
- Excessive regulations, licences, and approvals increase the time and cost of doing business.
- Small businesses are affected the most and this becomes an obstacle to the ease of doing business.
(c) Discourages Innovation and Entrepreneurship
- Excessive regulation and price controls reduce incentives to invest in new technology, innovation, and business expansion.
- Lower returns discourage productivity improvements and long-term economic growth.
Conclusion: Understanding economics
- Understanding economics systems and principles helps explain the choices of consumers, producers and government.
- It develops critical thinking, encourage the efficient use of resources, and helps in making informed decisions.
- Every economic decision affects individuals, society, and the economy.
- Market are dynamic and understanding them helps explain how they work in real life.
The Price Puzzle What Drives the Market Class 9 Short Notes
→ Black Marketing: Illegal buying and selling of goods at prices higher or lower than those fixed by the government.
→ Complementary Goods: Goods that are gene¬rally used together, such as cars and petrol.
→ Compliance: Following government rules, laws, licences, and regulations.
→ Consumer Welfare: Protection and promotion of consumers’ interests and well-being.
→ Demand: Quantity of a good or service that consumers are willing and able to buy at a given price.
→ Demand Curve: A graph showing the inverse relationship between price and quantity demanded.
→ Demand Schedule: A table showing quantities demanded at different prices.
→ Diminishing Marginal Utility: The principle that the additional satisfaction from consuming successive units of a product gradually decreases.
→ Dynamic Market: A market in which prices change continuously due to changes in demand and supply.
→ Ease of Doing Business: How simple it is to start, operate, and close a business in a country based on its regulations and administrative procedures.
→ Entrepreneurship: The ability to start and manage a business by taking risks.
→ Equilibrium Price: The price at which quantity demanded equals quantity supplied.
→ Equilibrium Quantity: The quantity bought and sold at the equilibrium price.
→ Excess Demand (Shortage): A situation where quantity demanded is greater than quantity supplied.
→ Excess Supply (Surplus): A situation where quantity supplied is greater than quantity demanded.
→ Hoarding: Accumulation of goods beyond immediate need, usually in anticipation of future shortages or to sell at higher prices in future.
→ Individual Demand: Quantity of a good or service demanded by a single consumer at different prices.
→ Individual Supply: Quantity of a good supplied by a single seller at different prices.
→ Innovation: Introduction of new ideas, methods, technologies, or products.
→ Marginal Utility: Additional satisfaction obtained from consuming one more unit of a good.
→ Market Demand: Total quantity demanded by all consumers in the market at different prices.
→ Market Equilibrium: The point where quantity demanded equals quantity supplied, with neither shortage nor surplus in the market.
→ Market Forces: The interaction of demand and supply that determines prices and quantities in a market.
→ Market Supply: Total quantity supplied by all sellers in the market at different prices.
→ Monopoly: A market structure in which a single seller controls the supply of a product or service and has significant power to control price.
→ Price Ceiling: A maximum price fixed by the government above which a seller cannot charge for a good or service.
→ Price Floor: A minimum price fixed by the government below which a good, service, or wage cannot be sold or paid.
→ Profitability: The ability of a business to earn profit.
→ Public Goods: Goods and services provided by the government for the benefit of all citizens, such as roads and parks.
→ Purchasing Power: A measure of how much one unit of currency can buy at a particular time.
→ Regulation: Government rules and laws to ensure fair market practices.
→ Regulatory Authority: A government body that regulates and supervises a particular sector of the economy.
→ Related Goods: Goods whose demand is interconnected, so a change in the price or availability of one affects the demand for the other.
→ Revenue: The total amount of money earned by a business from selling goods or services before deducting expenses.
→ Seasonality; Changes in demand or supply due to seasons, weather, festivals, or cultural habits.
→ Social Welfare: Measures taken to improve the well-being of society, especially vulnerable sections.
→ Substitute Goods: Goods that can replace each other, such as tea and coffee.
→ Supply: Quantity of a good or service that producers are willing and able to sell at a given price.
→ Supply Curve: A graph showing the direct relationship between price and quantity supplied.
→ Supply Schedule: A table showing quantities supplied at different prices.
→ Transparency: Openness and fairness in business and government activities.
→ Utility: Satisfaction obtained from consuming a good or service.