Experts have designed these Class 9 SST Notes and NCERT Class 9 SST Chapter 8 Building Blocks in Economics The Problem of Choice Notes for effective learning.
Class 9 Building Blocks in Economics The Problem of Choice Notes
Class 9 SST Chapter 8 Building Blocks in Economics The Problem of Choice Notes
Class 9 SST Chapter 8 Notes – Building Blocks in Economics The Problem of Choice Notes Class 9
- Economics focuses on the decisions people make when they cannot have everything they want.
- People, firms, and public authorities all have to decide how available resources should be used.
- Some human desires are needs, while others are wants.
- Needs are essential for survival, such as food, water and shelter.
- Wants provide additional satisfaction, such as gadgets, luxury items and vacations.
- Human wants are unlimited and continue to change over time.
Choices and Limited Resources
- Resources are needed to fulfil human needs and wants.
- Resources, both natural and human-made, are limited and required to produce goods and services, using the four factors of production land, labour, capital and technology.
- Since resources are scarce and have alternative uses, individuals, enterprises and governments must allocate them efficiently to maximise satisfaction and improve the living standards of people.
- Choosing one option means giving up another; this is known as opportunity cost.
- The Production Possibility Curve (PPC) shows different combinations using available resources efficiently. It shows trade-offs and opportunity cost and that maximum output can be achieved through efficient use of resources, and it serves as a useful tool for planning and decision-making.
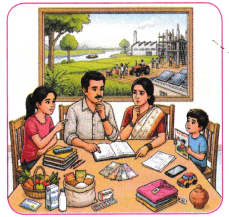
What Does Economics Deal With?
The word Economics comes from the Greek word ‘Oikonomia’, meaning household management.
It studies how limited resources are allocated and used efficiently to satisfy unlimited wants, and how individuals, enterprises and governments make economic choices that affect individuals and society.
Economics explains the interaction among different entities like producers, consumers, governments and financial institutions and studies wage earning, the distribution of wealth and resources, price determination in markets, and the role of education, technology, trade and government policies in shaping investment, prices and employment.

Economic decisions depend on data and analysis. Families plan how to spend and save their money, businesses study market trends to improve profits, and governments use tax revenue to fund public development and welfare initiatives.
Economists analyse alternatives, opportunity costs, risks and outcomes using government reports, economic surveys and financial statements, and contribute to policy-making by advising governments business consulting by helping firms grow and improve efficiency, research & education by studying economic trends and teaching, and finance by guiding investors on investment decisions.
Economic Survey: A Report On Indian Economy
Economic Survey is a yearly report issued by the Ministry of Finance and tabled in Parliament before the Union Budget.
It assesses India’s economic progress over the previous year and analyses key sectors such as agriculture, industry, services, employment, inflation, education, health and infrastructure.
It highlights future opportunities and challenges, guides policy decisions, acts as a blueprint for the Union Budget and helps citizens understand the economy.
Key Questions in Economics
Scarcity, caused by the imbalance between unlimited wants and limited resources, leads to three fundamental economic questions: What to Produce? How to Produce? For Whom to Produce?
What to Produce and for Whom?
This question determines which goods and services to produce, in what quantities, so as to satisfy the requirements of the economy within a specific time period.
Such decisions involve a trade-off between short-term economic gains and long-term sustainability, where choosing one option leads to the loss of benefits from another, known as opportunity cost (for example, benefits like water saving and improved soil health when choosing to cultivate millets instead of sugarcane).
Producers then take decisions by considering consumer demand, income levels, preferences and affordability, along with different production alternatives.
Similar decision-making is followed by firms, governments and consumers while allocating scarce resources.
The question of “for whom to produce” refers to identifying specific consumer groups based on needs, income levels and lifestyles, which influences product design and pricing.

For example, school shoes, formal office shoes, sports shoes and casual footwear are produced differently to suit different groups and their purchasing power.
Producers also vary materials and quality, such as leather or synthetic rubber, depending on whether products target high-income or more affordable segments.
Overall, the aim is to ensure efficient use of scarce resources while meeting diverse consumer needs.
How to Produce?
After deciding what to produce, producers choose the methods, resources and technology to be used, for instance a manufacturer may decide between using automation or relying more on labour to produce goods.
Production requires an appropriate combination of the factors of production, namely land, labour, capital and technology.
Production methods may be labour-intensive (more labour, less machinery) or capital-intensive (more machinery and technology).
Economic activities like agriculture and handicrafts generally rely more on labour, while industries such as steel and automobile manufacturing depend more on machinery.
The choice of technique depends on the cost and availability of labour and capital, level of technology, nature of the product, various factors of production and their relative cost, and government laws and regulations.
For instance, a garment manufacturer may use more labour if machines are expensive, or shift to automation if machines become cheaper and more affordable.

The use of advanced technology promotes machine-based production, whereas limited technological access results in manual production methods.
Clothing that is customised or designed requires skilled labour, while large-scale production of garments is more suitable for machinery.
When labour is inexpensive and easily available, firms prefer labour-intensive methods, but when labour is
expensive or scarce, they depend more on machines.
In addition, government laws and regulations like labour laws or incentives for machinery also influence the choice of production technique.
Economic Systems And How Choices Are Made
- An economic system is the way a country organises the production, distribution and consumption of goods
and services. It determines who owns resources, who makes economic decisions and how the three basic economic questions are answered. - Economic systems are classified into planned economy, market economy and mixed economy.
Planned Economy
- In a Planned Economy, major economic decisions are taken by acentral government authority’, which decides what to produce, in what quantity, how it should be produced, for whom it is produced and also set their prices.
- The government owns and controls most resources such as land, industries, banks and transport, while private ownership is limited.
- Firms operate according to state-set targets instead of consumer demand and must follow licensing and permit rules, which restrict entry into production activities.
- As a result, competition is limited, and there is little pressure on producers to improve quality or innovation.
- Examples: Former Soviet Union, North Korea and Cuba.

Market Economy
- In a Market Economy, economic decisions like w hat to produce, how to produce and the quantity of production are mainly guided by the forces of demand and supply, with limited government intervention.
- Resources such as factories, land, shops and other assets are largely owned by private individuals and enterprises, while the government mainly maintains law and order, and does not control pieces or production.
- Competition among producers encourages lower prices, better quality, innovation and efficiency.
- Examples: US, Japan and Hong Kong, even so the government still plays a role in the economy.

Mixed Economy
A Mixed Economy combines the features of planned and market economies, allowing both the government and private sector to participate in economic activities.
The private sector promotes profit, competition and innovation, while the government regulates the economy and provides public goods.
In a mixed economy, public sector enterprises play an important role.
Most economies have characteristics of a mixed system, with private ownership existing alongside some level of government regulation.
Examples: India (post-1991), China (post-1978), Sweden and Germany.
Even in countries like the US and Singapore, the government plays an important role in regulating and supporting market activities.
- After independence, India’s economy mainly followed a state-led or planned approach where the government had strong control over economic activities.
- The government managed industries, distributed resources, and controlled production through a system of licences and permits.
- Key sectors like transport, banking and heavy industries were largely under the public sector.
- By 1991, India faced major economic challenges, leading to the introduction of wide-ranging economic reforms.
- These reforms reduced strict controls, encouraged private participation, increased competition, and opened the economy to global trade and investment.
- As a result, India gradually moved towards a more market-oriented system, while the government ^ still continued to play an important role. Hence, today India is a Mixed Economy.
So, through this chapter you understood that economics is about making choices because resources are limited and wants are unlimited.
You understood that people, firms, and governments use resources carefully and consider opportunity cost.
The three main economic questions are what to produce, how to produce, and for whom to produce.
Different systems answer these questions differently, but most countries follow a mixed system.
These ideas help you understand how resources are produced, shared, and used in an economy.
Building Blocks in Economics The Problem of Choice Class 9 Short Notes
→ Capital-intensive Production: A production method that uses more machinery and technology than labour.
→ Competition: Rivalry among producers to attract consumers by offering better quality, lower prices or improved services.
→ Consumer: A person who uses goods and services to satisfy wants.
→ Data: Facts and figures collected for analysis and decision-making.
→ Demand: The quantity of a good or service that consumers are willing and able to buy at a given price and time.
→ Economic Entity: Any decision-making unit in an economy such as consumers, producers, enterprises or government.
→ Economic Survey: An annual report reviewing India’s economic performance, presented by the Ministry of Finance before the Union Budget.
→ Economic System: The way a country organises production, distribution and consumption of goods and services.
→ Economics: The study of how limited resources are used to satisfy unlimited human wants.
→ Economy: The condition of a country or region based on how goods and services are produced and consumed, and how money circulates within it.
Or
A system operating within a country or area that includes the production, distribution, trade, and consumption of goods and services.
→ Infrastructure: Basic facilities such as roads, transport, electricity, water supply and communication required for economic development.
→ Innovation: Introduction of new ideas, products or production methods to improve efficiency.
→ Labour-intensive Production: A production method that uses more labour than machinery.
→ Market Economy: An economy where demand and supply determine production and prices with limited government intervention.
→ Market: A system or place where goods and services are bought and sold.
→ Mixed Economy: An economic system where both the government and private sector participate in economic activities.
→ Opportunity Cost: The value of the next best alternative forgone when making a choice.
→ Planned Economy: An economy where the government decides production, allocation of resources and prices.
→ Policy: A planned course of action adopted by the government or an organisation.
→ Producer: A person or firm that produces goods and services.
→ Production Possibility Curve (PPC): A curve showing different combinations of two or more goods that can be produced with all available resources.
→ Public Goods: Goods and services available to everyone without exclusion, such as roads and street lights.
→ Resources: Inputs used to produce goods and services.
→ Scarcity: Situation where resources are limited but human wants are unlimited.
→ Supply: Quantity of a good or service that producers are willing to sell at a given price and time.
→ Survey: A systematic method of collecting and analysing information.
→ Trade-off: Sacrificing one option to gain another.