Practice with Understanding Society India and Beyond Class 9 Solutions and Class 9 Social Science SST Part 2 Chapter 5 Managing Your Personal Social Science Question Answer NCERT Solutions to improve your exam performance.
Managing Your Personal Class 9 Questions and Answers
Class 9 Managing Your Personal Question Answer
The Big Questions? (Page No. 107)
Question 1.
What is personal finance and why is it important for individuals?
Answer:
Personal finance is the planning and management of an individual’s money to meet needs and wants. It is important because individuals and households have to make decisions about spending, saving, investing, and preparing for future needs. Good financial management helps people use money efficiently and work towards goals such as education, a house, or emergencies.
Question 2.
What are the pillars of personal finance?
Answer:
The five pillars are income, budgeting, saving, investing, and protection/risk management. Income provides money to manage; budgeting plans spending and saving; saving sets money aside for future needs; investing aims to grow savings; and protection safeguards money and assets against risks.
Question 3.
What are some common savings and investment options?
Answer:
Common savings and investment options include:
- Fixed Deposits (FDs)
- Public Provident Fund (PPF)
- National Savings Certificate (NSC)
- Sukanya Samriddhi Yojana
- Bonds
- Stocks or shares (equity)
- Mutual funds
These options differ in terms of risk, return, time horizon, and liquidity.
Question 4.
How can you protect your savings and assets?
Answer:
Savings and assets can be protected through insurance and responsible financial management. Insurance provides financial support for specified losses such as medical expenses, death, vehicle damage, property damage, crop loss, or cattle loss. Responsible borrowing and maintaining emergency savings also support financial security.
Question 5.
What is income tax?
Answer:
Income tax is a direct tax paid on taxable income earned during a financial year, subject to the applicable rules and exemptions. The chapter explains a slab system in which different portions of taxable income are taxed at different rates.
Managing Your Personal Question Answer Class 9
InText Questions
Let’s Explore
Question 1.
Think of all your expenses and prepare your monthly/weekly budget using the below template. (Page No. 109)
| Expenses | Amount |
| School bag Books Uniform and shoes Notebooks Pens Pencils Art supplies |
₹ ₹ ₹ ₹ ₹ ₹ ₹ |
| Total Expenses | ₹ |
| Savings | ₹ |
Answer:
| Total Amount | ₹5,000 |
| Expenses | Amount |
| School bag | ₹ 800 |
| Books | ₹ 1,000 |
| Uniform and shoes | ₹ 1,200 |
| Notebooks | ₹ 500 |
| Pens | ₹ 150 |
| Pencils | ₹ 100 |
| Art supplies | ₹ 400 |
| Total Expenses | ₹ 4,150 |
| Savings | ₹ 850 |
| Total Amount | ₹ 5,000 |
I would spend ₹ 4, 150 on my school needs and save ₹ 850 for future use.
Question 2.
(a) In the given figure, the curves are flatter in the beginning and tend to become steeper in the later years. Why do you think that happens?
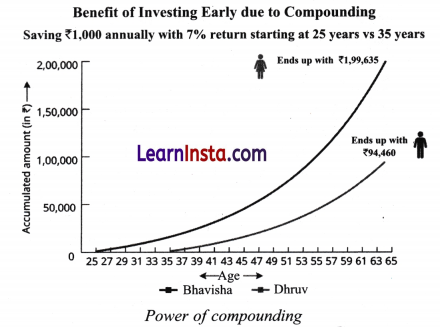
The curves are flatter in the beginning because the investment earns smaller returns at first. As time passes, compounding allows the returns to earn further returns, so the accumulated amount grows faster. Therefore, the curves become steeper in the later years.
(b) Talk to your parents and find out the fixed deposit rates of their bank. You can also refer to the bank’s website.
Answer:
Do it yourself.
Let’s Analyse
Question 1.
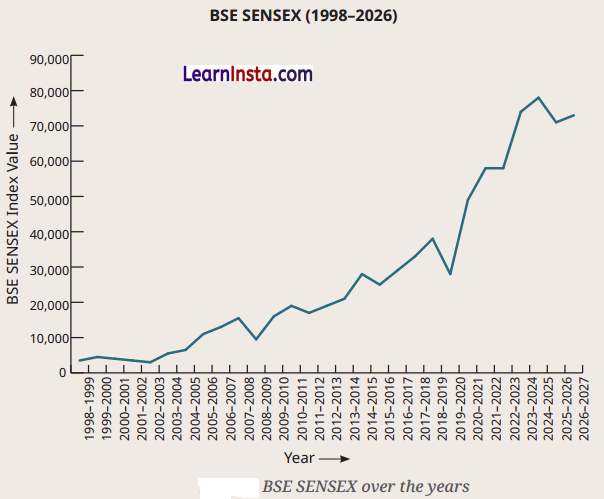
Look at the graph below that displays the performance of BSE SENSEX over the years. It fluctuates over short time periods; however, it can go up significantly in the long run. Why do you think these fluctuations happen? Discuss possible reasons with your classmates and find out more from newspapers, the internet, or by speaking to your family members. (Page No. 114)
Answer:
The fluctuations in the BSE SENSEX happen because stock prices keep changing according to market conditions. Changes in the economy, company performance, investor expectations, and other events can cause prices to rise or fall. Therefore, the SENSEX may fluctuate in the short term, while it can increase significantly over a longer period.
Question 2.
Sai’s taxable income is 3,80,000 in a financial year. How much income tax does he have to pay according to the tax slabs given below? (Page No. 120)
Calculation of Income Tax as Per the Tax Slabs
| Portion of Income in the Tax Slab | Tax Rate | Tax on that Portion of Income |
| Up to 4,00,000 | 0% | 0 |
| ₹ 4,00,001 – ₹ 8,00,000 (next ₹ 4,00,000) |
5% | 5% of ₹ 4,00,000 = ₹ 20,000 |
| ₹8,00,001 – ₹12,00,000 (next ₹4,00,000) |
10% | 10% of ₹ 4,00,000 = ₹ 40,000 |
| ₹ 12,00,001 – ₹ ï3,25,000(remaining ₹ l,25,000) | 15% | 15% of ₹ l,25,000₹ l8,750 |
| Total Tax | ₹ 78750 |
Answer:
Sai’s taxable income is ₹ 3,80,000. According to the given tax slabs, income up to ₹ 4,00,000 is taxed at 0%. Income tax = ₹ 0.
Question 4.
Ask your parents, relatives, or a person in your neighbourhood if they file personal income tax returns. Make a small report on the procedure to file an income tax return. You may refer to the following website: https://incomeraxindia.gov. in! Pages/tax-services/file- income-tax-return. ospx (Page No. 120)
Answer:
Do it yourself.
Think About It
Question 1.
Have you ever thought about earning your own money? What kind of skill would you require and which work would you choose? (Page No. 108)
Answer:
Do it yourself
Question 2.
There are many ‘Earn While You Learn’ programmes that allow college students to continue their education while earning an income through part- time work, internships, or apprenticeships. This not only provides financial support but also helps them gain practical skills, work experience, and a better understanding of the real-world workplace.
(Page No. 108)
Answer:
Earn While You Learn programmes allow college students to continue their education while earning an income through part-time work, internships, or apprenticeships. These programmes provide financial support and help students gain practical skills, work experiences, and a better understanding of the real-world workplace.
Question 3.
Suppose you and your friends need to buy new badminton rackets for an upcoming tournament because the old ones have worn out. How would you manage your budget to cover the cost? Would you cut back on other expenses, use your savings, or borrow the amount from your parents or friends? (Page No. 109)
Answer:
Do it yourself.
Question 4.
What would you do if you received ₹ 100 today? Would you save some or all of it? Or spend it right away? (Page No. 111)
Answer:
I would save some of the money for future needs and spend the rest on something useful rather than spending it all immediately.
Question 5.
In the Grade 9 Part I Chapter ‘Building Blocks in Economics: The Problem of Choice’, you learnt about wants and needs. Would you prefer spending the money on a want or a need? (Page No. 111)
Answer:
I would prefer spending the money on a need rather than a want, because needs are essential while wants can be postponed.
Question 6.
Financial experts often suggest saving first and spending what is left. Do you agree? (Page No. 111)
Answer:
Yes, I agree. Saving first helps us set aside money for future needs and emergencies, and then we can spend what remains.
Question 7.
Do you think individuals with low income can also save? Why or why not? (Page No. 111)
Answer:
Yes, individuals with low income can also save. Even if they can save only a small amount, regular saving can help them meet future needs and emergencies.
Question 8.
Have you heard this disclaimer in mutual fund advertisements on the television? “Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing.” Why do you think this is included? (Page No. 115)
Answer:
This disclaimer is included because mutual fund investments are subject to market risks. Investors should therefore read all scheme-related documents carefully before investing.
Question 9.
Have you ever heard your parents say, “This month’s EMI has been paid”? An EMI (equated monthly instalment) is the fixed amount of money a person pays every month to repay a loan. Suppose a family buys a refrigerator costing ₹30,000 but does not want to pay the entire amount at once. In such a case, they may take a loan and repay it through an EMI of ₹ 3,000 every month for 12 months. Each EMI includes a portion of the original loan amount (the principal) as well as the interest charged by the lender. EMIs are commonly used to purchase mobile phones, household appliances, two-wheelers, homes, and cars.
(a) Why might a family choose to buy something on EMI even if it costs more in the long run?
(b) Can having too many EMIs affect savings and emergency funds? (Page No. 117)
Answer:
(a) A family may choose EMI because it allows them to pay for the item in smaller monthly amounts instead of paying the entire amount at once.
(b) Yes. Too many EMIs can reduce the amount of money available for savings and emergency funds, making it harder to manage future financial needs.
Class 9 SST Part 2 Chapter 5 Question Answer
Questions and Activities (Page No. 121 – 123)
Question 1.
Why is managing money wisely important for all individuals irrespective of their income?
Answer:
Managing money wisely is important because it helps individuals plan expenses, control unnecessary spending, save for future needs, invest wisely, protect against risks, borrow responsibly, and achieve financial stability.
Question 2.
How can budgeting help people balance their present needs with their future financial goals? Give examples.
Answer:
Budgeting helps people balance present needs and future goals by planning how much to spend and save. For example, a person can pay for daily needs while saving money for a school trip, sports equipment, higher education, or emergencies.
Question 3.
School Reopening Budget Activity
Your parents have given you ₹ ‘3,000 to prepare for the new school year. Make a list of the items you need, find out their prices (by visiting local stores or asking a parent or teacher), and prepare a budget. Calculate the total cost and check whether it stays within ₹ 3,000.
If your total is less than ₹ 3,000, you may add one additional item of your choice.
If your total exceeds ₹ 3,000, decide which item(s) you can postpone or avoid buying to stay within your budget.
Use the budget template provided and ensure that all expenses are accurately calculated.
School Reopening Budget
| Expenses | ₹ 3000 |
| School bag Books Uniform and shoes Notebooks Pens Pencils Art supplies |
₹ ₹ ₹ ₹ ₹ ₹ ₹ |
| Total Expenses | ₹ |
| Savings | ₹ |
Answer:
Do it yourself.
Question 4.
Why is saving alone often not enough to build wealth in the long run? How do investments help increase the value of money over time?
Answer:
Saving alone may not be enough because the value of money can decrease due to inflation. Investments can help money generate returns and grow over time, helping to protect its value.
Question 5.
Investment Planning
Activity: Suppose you received cash gifts worth ₹ 3000 on your last birthday and decided to save ₹ 1500. With the help of your teacher, calculate the returns you might have earned if you had invested this amount in different combinations of investments. For example, what returns would you have received if you had invested ₹ 500 in a fixed deposit, ₹ 800 in the stock market, and ₹ 200 in gold? Try other combinations and find information on the returns from different investment options using reliable sources, such as newspapers, magazines, or official websites. Based on your findings, prepare an investment plan explaining why you think each investment option is suitable or unsuitable.
Answer:
Do it yourself.
Question 6.
How does inflation affect the value of money over time? Why should people consider inflation while making financial decisions?
Answer:
Inflation increases the prices of goods and services and reduces the purchasing power of money. People should consider inflation because the same amount of money may buy fewer goods and services in the future.
Question 7.
Different investment options involve different levels of risk and return. Do you think taking higher risks is always the best way to earn higher returns? How should a person decide which investment option is most suitable for them?
Answer:
No, taking higher risks is not always the best choice. A person should choose an investment according to their financial goals, the amount of risk they are willing to take, and when they will need the money.
Question 8.
Why do people buy insurance policies even though they may never face a major loss? How does insurance provide financial security?
Answer:
People buy insurance to protect themselves against unexpected events such as illness, accidents, loss of income, or property damage. Insurance provides financial compensation for covered losses and reduces the financial burden during emergencies.
Question 9.
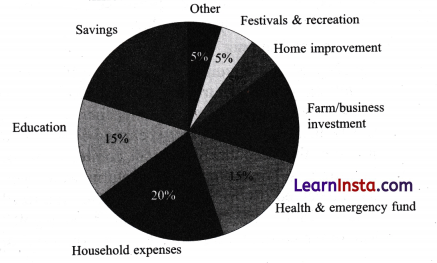
Imagine your family receives ₹ 1,00,000 from farming, a small business, livestock sales, and savings. Help your family decide how to use the money wisely.
Step 1: Prepare a Budget
Allocate the ₹ 1,00,000 among the following categories:
| Category | Amount (₹) | Percentage (%) |
| Savings | ||
| Education | ||
| Household expenses | ||
| Health and emergency fund | ||
| Farm or business investment | ||
| Home improvement | ||
| Festivals and recreation | ||
| Other | ||
| Total | 1,00,000 | 100% |
Step 2: Needs vs Wants
Classify each expense as a need or a want and give a reason.
Examples:
- School fees
- New mobile phone
- Better seeds or livestock feed
- Festival celebrations
- Water storage tank 5- Managing Your
Step 3: Save for the Future
Suppose your family saves 30,000 at 8% compound interest per year.
Using the formula A = P(1 + r)n, where A: Amount,
P: Principal, r: Rate of compound interest, n: number of years,
calculate:
- The amount after 5 years.
- The interest earned.
Step 4: Save First, Spend Later
Many financial experts recommend:
Expenses = Income – Savings
If your family receives ₹ 1,00,000 and saves ₹ 20,000 first, only ₹ 80,000 is available for spending. This helps
ensure that future needs and emergencies can be met.
Step 5: Reflect
1. What percentage of the money did you save?
2. Which expenses were needs and which were wants?
3. How can savings improve a family’s financial security?
4. How does compound interest help money grow?
Challenge: Create a pie chart showing how the ₹ 1,00,000 was allocated across different categories.
Answer:
Step 1: Prepare a Budget
| Category | Amount (₹) | Percentage (%) |
| Savings | 20,000 | 20% |
| Education | 15,000 | 15% |
| Household expenses | 20,000 | 20% |
| Health and emergency fund | 15,000 | 15% |
| Farm or business investment | 15,000 | 15% |
| Home improvement | 5,000 | 5% |
| Festivals and recreation | 5,000 | 5% |
| Other | 5,000 | 5% |
| Total | 1,00,000 | 100% |
Step 2: Needs vs Wants
- School fees – Need, because education is essential.
- New mobile phone- Want, if the existing phone is working.
- Better seeds or livestock feed – Need, because they support farming and income.
- Festival celebrations – Want, because they are not essential.
- Water storage tank – Need, if it is required for regular household use.
Step 3: Save for the Future
Given: P = ₹ 30,000
r = 8% = 0.08
n = 5 years
Formula: A = P(1 + r) n
A = 30,000 × (1 .08) 5
A ≈ ₹ 44,080
1. Amount after 5 years = ₹ 44,080
2. Interest earned = ₹ 44080 – ₹ 30,000 = ₹ 14,080
Step 4: Save First, Spend Later
If the family receives 1,00,000 and saves 20,000 first:
Expenses = Income – Savings = ₹ 1,00,000 – ₹ 20,000 = ₹ 80,000
So, ₹ 80,000 is available for spending.
Step 5: Reflect
1. What percentage of the money did you save?
Answer:
20%
2. Which expenses were needs and which were wants?
Answer:
Education, household expenses, health and emergency needs, and farm/business investment are needs. Festivals and recreation are wants.
3. How can savings improve a family’s financial security?
Answer:
Savings help meet future needs and emergencies and provide financial security.
4. How does compound interest help money grow?
Answer:
Compound interest allows the returns already earned to generate additional returns, helping money grow over time.